Note 16 | Venture Investors Should Put Capital and Attention Into Companies They Understand
These are Robin Shen’s original reading notes and commentary, written in his own words after reading Tren Griffin’s A Dozen Lessons for Entrepreneurs. They are not the original book, excerpts from it, or an official publication. Methods and concepts from the book are attributed to Tren Griffin; other sources are identified where stated. For reference only; not investment advice.
English translation of Robin’s Chinese reading notes and commentary. Passages are paraphrased, not verified verbatim quotations from the original English edition.
A Dozen Lessons for Entrepreneurs — Chapter 16, “Bill Gurley: Benchmark” (Part II, “The Venture Capitalists”)
The book describes Bill Gurley as having spent more than ten years as a partner at Benchmark, following work as a research analyst and at another venture capital firm. These descriptions reflect the time when the book was written. His recurring emphasis is that venture investors should put limited capital and attention into companies they truly understand, rather than make predicting the broader environment their main job.
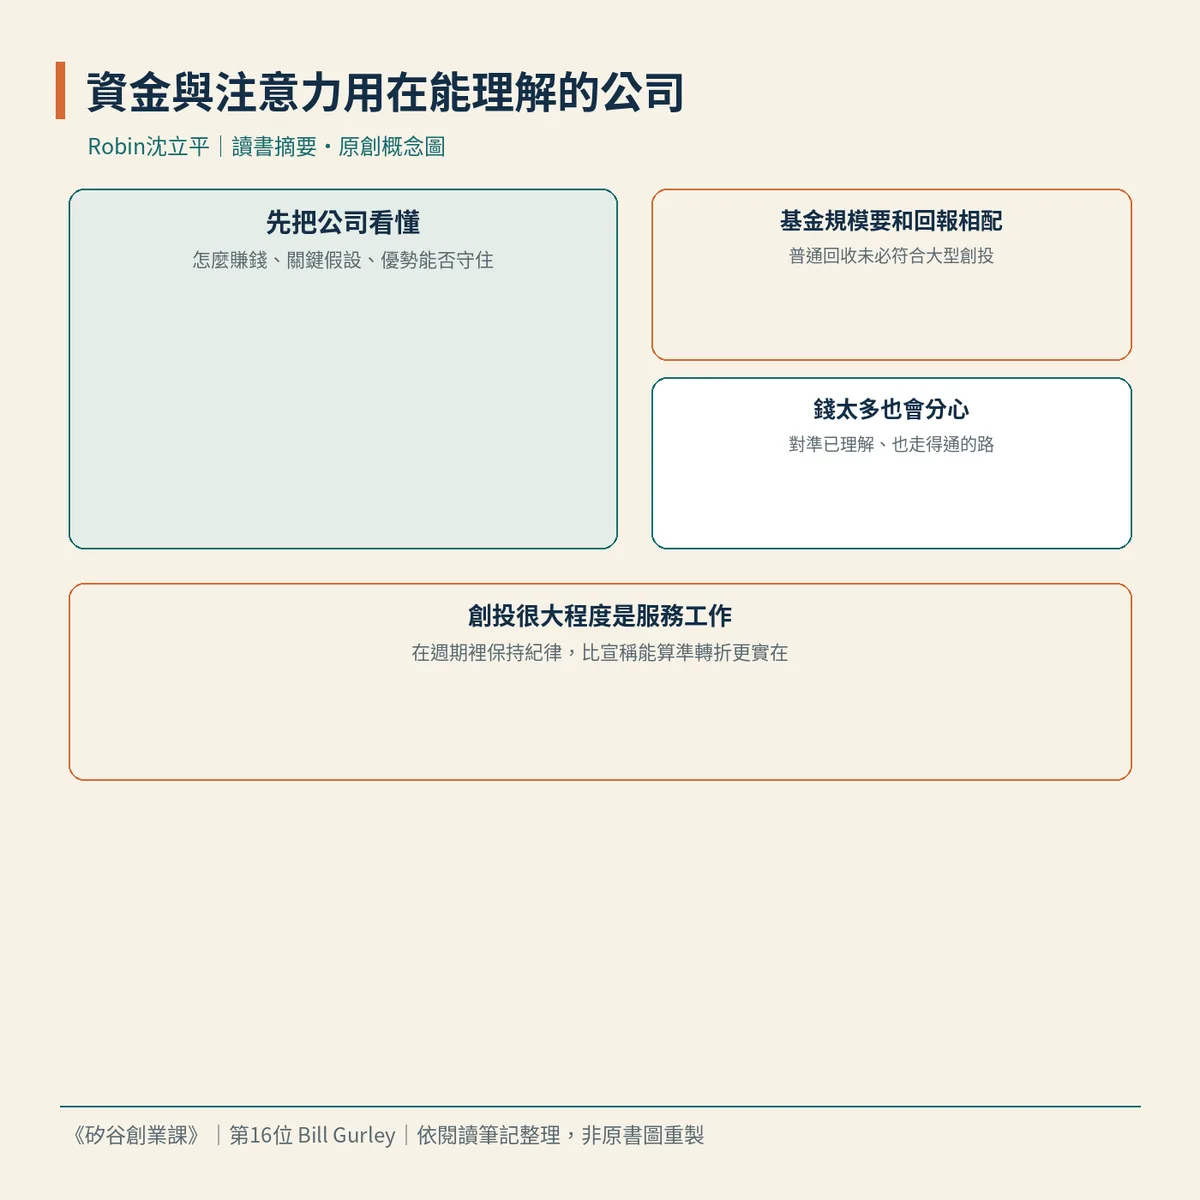
Gurley cites the view that outstanding investors do not make macroeconomic research their primary work. The author explains that assessing whether a company could deliver sufficient returns usually offers a better chance of useful insight than predicting the entire economy. The environment certainly exists, but where you can go deep is how an individual company makes money, what its key assumptions are, and whether its advantages are defensible. Young companies are particularly prone to “complete-looking financial statements with inputs that cannot stand up to questions.” Tools such as discounted cash flow (DCF) are not necessarily flawed, but unreliable inputs produce unreliable results. A moat also needs to be tested by whether the company can consistently earn returns above its cost of capital. A high price or temporary strength does not establish a real barrier. If supply can increase without limit, prices will eventually be pushed down.
Capital itself must fit this understanding. Large venture capital funds need outcomes large enough to affect the performance of the whole fund. The number of companies they can look after simultaneously is limited, so ordinary-sized proceeds may not meet their requirements. Businesses with smaller capital needs may be better served by bank loans, internal cash, or money from friends and family. Conversely, too much money can also create problems. Gurley believes startups often lose focus and spread resources in unnecessary directions because they cannot absorb excess capital, rather than because they lack money. The point is not to minimize cash, but to direct every dollar toward a path you understand and that works.
Much of venture capital’s daily work is service and selling, rather than sitting in a conference room thinking about strategy. Good investors need to sell themselves, their resources, and their services, and actually get things done for portfolio companies. If they are neither good at nor willing to do these things, the job may not suit them. Venture capital is also cyclical. Both optimism and pessimism will arrive. The author relays that most things have cycles; those who still have capital and maintain discipline during short-term pessimism may find opportunities. Preparing the capital and habits to get through headwinds is more practical than claiming to predict turning points precisely.
The conclusion: first focus on companies you can truly understand, clarify the assumptions behind their business models and the advantages they can defend, then align fund size with the returns being pursued. There must be enough money, but not so much that it distracts the company. Investors’ work is to provide practical services through cycles, rather than predict every turn in the broader environment.
One deeper insight
I think the more complete a new company’s presentation is, the easier it is to believe you already understand it. Better questions are: How exactly does this company make money? Which assumptions would bring down the whole story if they failed? Are we actually spending time on those questions?
Three suggestions
First, choose a company you are evaluating or building. Use one page to explain how it makes money, its three most important assumptions, and the evidence currently supporting them. If the assumptions exist only as deductions from financial statements, return to deepening your understanding of the company itself.
Second, check whether current capital strengthens a path you already understand or spreads attention toward directions you have not thought through. If it is the latter, write down what you plan to stop or postpone and whether the core business would actually suffer without that work.
Third, if you are an investor or are choosing one, list what the investor can actually do for the company beyond providing money, and what capital and discipline both sides have prepared for a cooling market. If you cannot name concrete services, do not treat “finding venture capital” as a next step you already understand.
#ADozenLessonsForEntrepreneurs #BillGurley #ReadingNotes
These are reading notes and reflections based on my personal understanding. I recommend reading them alongside the original book for the full context.
Comments
What do you think? Share your experience or questions.
Sign in to comment, reply or like. Sign in / Sign up
Loading comments…