Note 15 | Do Not Copy What Facebook Did. Find Your Own Questions
These are Robin Shen’s original reading notes and commentary, written in his own words after reading Eric Ries’s The Lean Startup: How Today's Entrepreneurs Use Continuous Innovation to Create Radically Successful Businesses. They are not the original book, excerpts from it, or an official publication. Methods and concepts from the book are attributed to Eric Ries; other sources are identified where stated. For reference only; not investment advice.
English translation of Robin’s Chinese reading notes and commentary. Passages are paraphrased, not verified verbatim quotations from the original English edition.
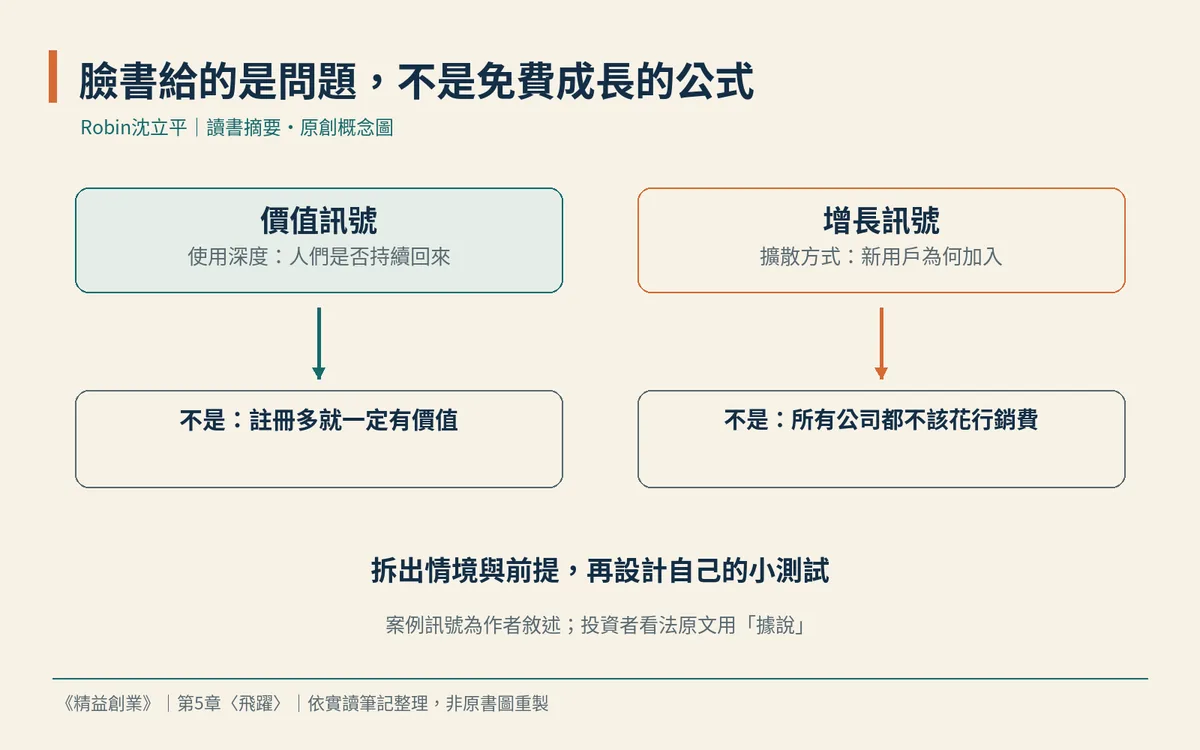
Why might a company with very little early revenue still be worth investing in? In Chapter 5, Eric Ries uses Facebook’s beginnings to remind readers that the answer is not only “the next large market” or the founders’ charisma, but what evidence of behavior at the time gave reason to believe the premises of value and growth. That is the question to bring to a case, and it matters more than imitating the appearance of a successful company.
As Ries narrates, Facebook in its early days was live only at a few universities, with about 150,000 registered users, slim revenue, and more fully featured campus social products already on the market. With the qualifier “reportedly,” he notes that investors paid special attention to two things: users were highly active, and the service could spread rapidly on campus. This is not an investment record independently verified by this note. It is a historical case the book uses to unpack the question.
The signals described in the book include more than half of users visiting every day, and, without spending on advertising, reaching nearly three-quarters of Harvard undergraduates within a month of going live. The former leads one to ask whether the product created real value; the latter, how new users were attracted. The two signals do not answer the same question: many people having tried something is not the same as being willing to use it often; a few people loving it is not the same as a path to expansion already being established.
At the time, some also questioned the lack of revenue and the absence of a business model. Ries’s analysis is that not every site that attracts attention should be treated as the same: if acquiring users does not depend on continued spending, and usage is high, the engine behind it may differ from that of a company that buys traffic with capital. This passage should not, however, be expanded into “as long as there are users, revenue can be ignored,” still less used as a guarantee of any valuation on the strength of early activity.
Ries immediately argues against copying. Some infer from the case that you should not charge early, or that marketing should never spend money, which is precisely to miss the point. Opposite success cases can be found in different situations; founders have to find, by experiment, the arrangements that work in their own. The value of a strategy is that it poses the right questions, not that it moves someone else’s answers unchanged into your budget and product plan.
Likewise, “being in the right place at the right time” is not a sufficient explanation. Ries points out that many companies faced the same opportunity and still failed, and that Facebook was not without leading competitors. If you only select stories by success or failure after the fact, you ignore how the successful identified which premises were working and which were misleading them. What can be borrowed is the ability to correct judgment, not timing as an excuse for exemption from testing.
Looking for questions, however, can also become an excuse for delay. At one extreme, a little demand is heard and development begins at once; at the other, research is continually added and plans rewritten, and real interaction is never touched. Ries’s view is that many plans fail not because the strategic principles are poor, but because the facts they rest on are skewed; such distortions often surface only when the product meets users, and no amount of whiteboard reasoning can replace that.
The chapter hands the balance between the two extremes to the minimum viable product, which is taken up next. I think the most practical lesson for early investment is this: there can be important evidence besides revenue, but each piece of evidence has to state clearly what it answers and what it has not yet answered. Do not put blind faith in current revenue, and do not put blind faith in the legend of a star company. First make the key questions observable, and only then discuss why the company is worth continued investment.
Three suggestions
For your own product, choose one value behavior and one growth behavior, write down the expectation and whom you will observe, and do not treat a large number of registrations and continued use as the same thing.
Pick a benchmark case you often cite, take apart its customer group, method of acquisition, and founding premises, then check which conditions differ from yours, and do not copy a pricing or marketing policy directly.
Set an end point for the current analysis, and at that point reach users with a small, testable version. If unknowns remain, list them clearly as questions for a test, rather than postponing action indefinitely.
#TheLeanStartup | Source: Chapter 5, “Leap”
These are reading notes and reflections based on my personal understanding. I recommend reading them alongside the original book for the full context.
Comments
What do you think? Share your experience or questions.
Sign in to comment, reply or like. Sign in / Sign up
Loading comments…