Note 31 | The Cost of Startup Leadership Includes Time, Relationships, and Responsibility
These are Robin Shen’s original reading notes and commentary, written in his own words after reading Tren Griffin’s A Dozen Lessons for Entrepreneurs. They are not the original book, excerpts from it, or an official publication. Methods and concepts from the book are attributed to Tren Griffin; other sources are identified where stated. For reference only; not investment advice.
English translation of Robin’s Chinese reading notes and commentary. Passages are paraphrased, not verified verbatim quotations from the original English edition.
A Dozen Lessons for Entrepreneurs — Chapter 31, “Heidi Roizen: Draper Fisher Jurvetson” (Part II, “The Venture Capitalists”)
The book describes Heidi Roizen as an operating partner at Draper Fisher Jurvetson (DFJ) at the time, having previously cofounded a company and served as its chief executive officer (CEO), and worked in developer relations at Apple. These descriptions reflect the time when the book was written. Her discussion of leadership goes beyond whether there is enough money. She counts the assumptions behind the numbers, financing terms, responsibility to employees, time, and relationships among the costs of entrepreneurship.
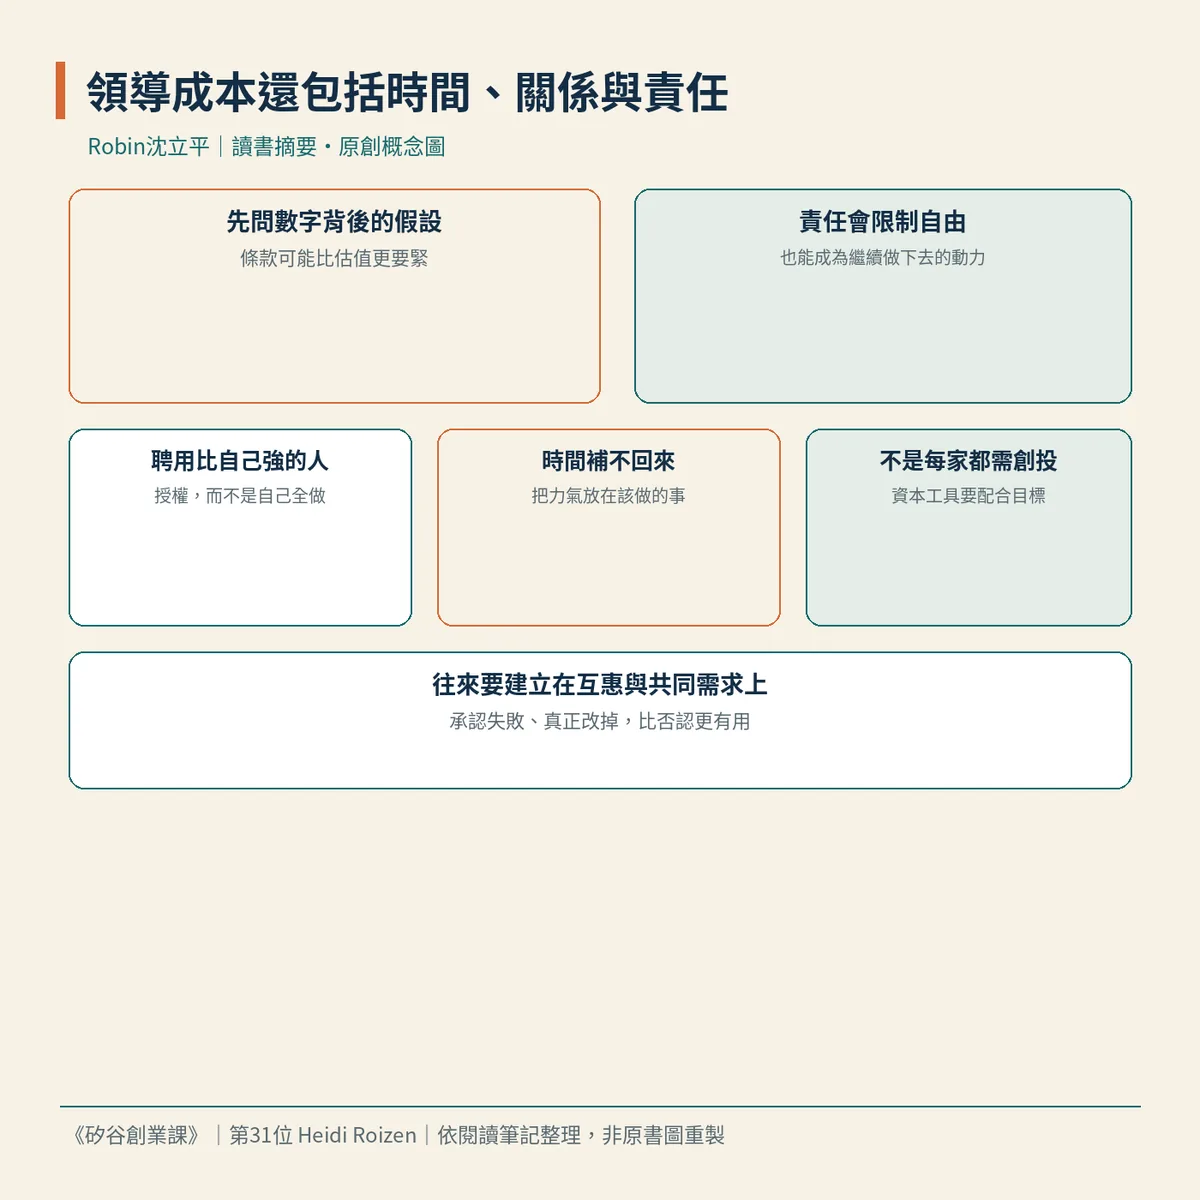
Roizen cautions that the assumptions and sensitivities behind financial numbers often matter more than the headline figures. Ask where the numbers come from, what happens if they come in at half or twice the amount, and what could bring the company down. A spreadsheet is only the output of a set of assumptions. Unreliable inputs produce unreliable conclusions. In fundraising, terms can matter more than valuation. Founders who look only at how much equity they sell and how much cash arrives, without understanding liquidation preferences and payment priority, can easily misunderstand what they will actually receive. The author also cautions that an attractive office is not necessarily the best use of the money.
Responsibility limits freedom, but can also motivate. Roizen recalls that when her company had roughly 100 employees, she would count cars in the parking lot on her way in each day and think about those people’s car loans and livelihoods. Other employees also worried about one another’s lives. When a crisis came, some stayed to get through it together and others left. Entrepreneurship is teamwork, yet still brings loneliness and unavoidable trade-offs. Work, family, and oneself cannot always receive equal priority. Leaders need to hire people better than themselves and genuinely delegate. If the head of sales knows less about sales than the founder, the arrangement itself is flawed. Great people attract more great people. Time is the hardest resource to replenish, so effort should go toward what truly needs doing.
Not every company needs venture capital. Some businesses can start with savings or bank loans and deliver very good returns. Only when the goal calls for venture-scale expansion does a company really need risk capital to match. After failure, acknowledge it, make repairs, and avoid repeating the mistake. Things beyond one’s control will still happen. Accepting reality and adapting is more useful than denial. Relationships center on connection and reciprocity, rather than treating every interaction as a transaction from the start. Negotiation is similar: seek the greatest overlap in both sides’ needs, rather than place all hope in clever terms. Legal documents remain necessary, but without substantive agreement, terms alone can rarely sustain a relationship.
The conclusion: startup leadership costs more than money. It also takes time, responsibility for people, and how you deal with others. Understand assumptions and terms first, hire stronger people and delegate, then decide whether the business actually needs venture capital. Build relationships and negotiations on reciprocity and shared needs. Acknowledge failures and make real changes.
One deeper insight
I think valuation is the easiest number to make prominent in fundraising discussions, while terms, assumptions, and responsibility to employees often get pushed into footnotes. Without accounting for those costs, more money in the bank does not necessarily make a company safer. Sometimes it simply makes the commitments heavier.
Three suggestions
First, break the current financial forecast into a few key assumptions. Write down where the company would first run into trouble if the figures came in at half the level or suddenly doubled. If you cannot explain where a number comes from, do not yet treat it as a sound plan.
Second, if you are negotiating funding, list not only valuation but also liquidation preferences and other terms affecting payment priority, and what you can actually retain. Also describe where the money will go, to avoid first making the company look bigger on the surface.
Third, review two lists: people stronger than you to whom you are willing to delegate, and activities that regularly consume your time but may not be yours to do. Also write down whether this business must use venture capital or could start with other funding, so the goal matches the financing tool.
#ADozenLessonsForEntrepreneurs #HeidiRoizen #ReadingNotes
These are reading notes and reflections based on my personal understanding. I recommend reading them alongside the original book for the full context.
Comments
What do you think? Share your experience or questions.
Sign in to comment, reply or like. Sign in / Sign up
Loading comments…