Note 34 | Venture Capital Preserves the Chance of a Few Big Winners Rather Than Scaling Every Company Equally
These are Robin Shen’s original reading notes and commentary, written in his own words after reading Tren Griffin’s A Dozen Lessons for Entrepreneurs. They are not the original book, excerpts from it, or an official publication. Methods and concepts from the book are attributed to Tren Griffin; other sources are identified where stated. For reference only; not investment advice.
English translation of Robin’s Chinese reading notes and commentary. Passages are paraphrased, not verified verbatim quotations from the original English edition.
A Dozen Lessons for Entrepreneurs — Chapter 34, “Fred Wilson: Union Square Ventures” (Part II, “The Venture Capitalists”)
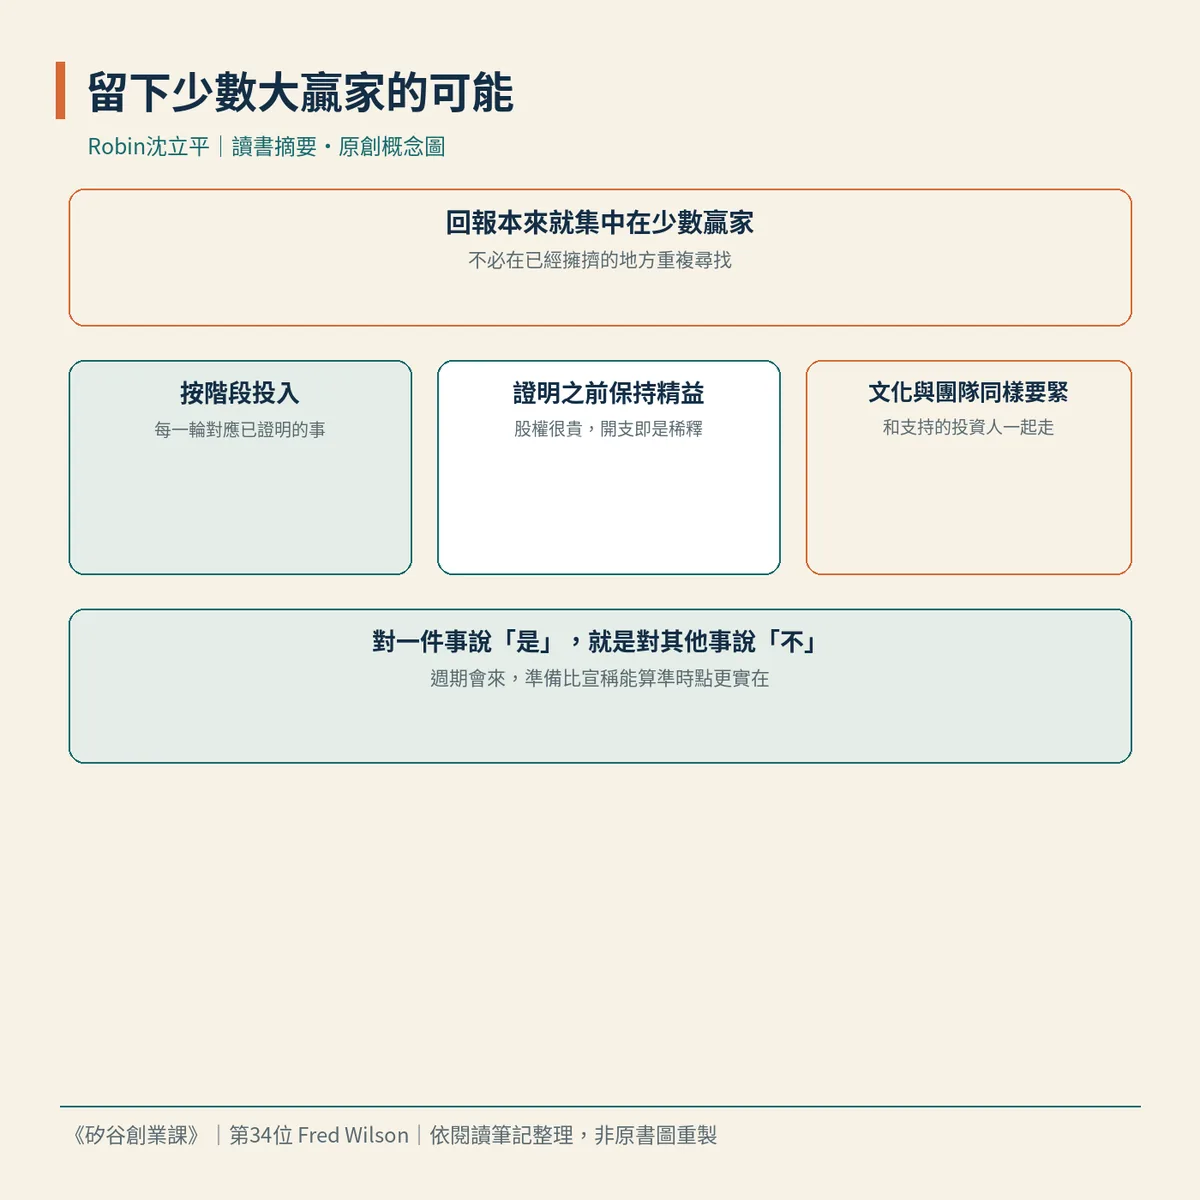
The book describes Fred Wilson as a partner at Union Square Ventures. This description reflects the time when the book was written. In his view, venture capital is not about growing every portfolio company equally. It is about using pacing and discipline to preserve the few opportunities that could become truly large. Returns are inherently concentrated, funding should proceed in stages, and companies should not scale aggressively before products and people are proven. Through the cycle, investors must also consider both the companies and their own opportunity costs.
Wilson points out that venture returns concentrate in a few winners. That is all the more reason not to keep looking only in crowded places where everyone searches for the keys under the same streetlight. Funding should follow verifiable milestones and stages. From the early days through expansion, each round should correspond to what has been proven, rather than commit all resources at the outset based on the ultimate vision. Before the product, people, and processes are proven, companies should not hire at scale or burn money too quickly. Equity capital is expensive; each expenditure comes with dilution. Lean must become a culture, not just a methodology. The initial team’s cohesion, culture, mission, and values matter as much as product design. Entrepreneurship requires full commitment, and courage is contagious. A founder’s job is difficult to begin with, and an investor willing to offer real support helps. Reputation is a magnet. Treating people well builds trust that supports future relationships.
Saying “yes” to one investment also means saying “no” to others. Investors’ time and capital carry opportunity costs. They must acknowledge this rather than pretend they can accept every promising deal. Venture capital cycles are often more extreme than those of the broader market. Turning points cannot be predicted precisely, but investors can prepare in advance and help companies navigate stretches that are too hot as well as too cold. The author cautions that a fund’s required returns, a company’s fundraising valuation, and how management costs and returns are calculated must be considered separately. They cannot be blended into one number and used to push every company to grow in lockstep.
The conclusion: venture capital preserves the chance of a few big winners by investing in stages, staying lean before validation, and treating culture and team as equally important to the product. Saying “yes” has a cost. Cycles will come. Preparation and discipline are more practical than claiming to predict the timing precisely. Growing every company at the same pace may instead use up the opportunities most worth preserving.
One deeper insight
I think the line that comes up most readily in a portfolio discussion is “This company should accelerate too.” We should first ask whether its product and people are proven enough to warrant acceleration, and which potentially better option we forgo by saying yes to this one. If we skip both questions, increasing commitments across the board simply spends our discipline.
Three suggestions
First, write down the verifiable stage of each current portfolio company or company under consideration, and what the next investment should prove. Do not try to fill unproven gaps by hiring large numbers of people.
Second, calculate the dilution associated with the latest expenditure and whether it genuinely strengthens the product, processes, or people. If it merely makes the company look bigger, stop first and put lean practices back into everyday work, not just slogans.
Third, before saying “yes” to an investment, list the alternatives you are giving up and what both the company and your own firm have prepared if the cycle turns cold. If you cannot describe the opportunity cost, it is not yet a decision made with a considered pace.
#ADozenLessonsForEntrepreneurs #FredWilson #ReadingNotes
These are reading notes and reflections based on my personal understanding. I recommend reading them alongside the original book for the full context.
Comments
What do you think? Share your experience or questions.
Sign in to comment, reply or like. Sign in / Sign up
Loading comments…